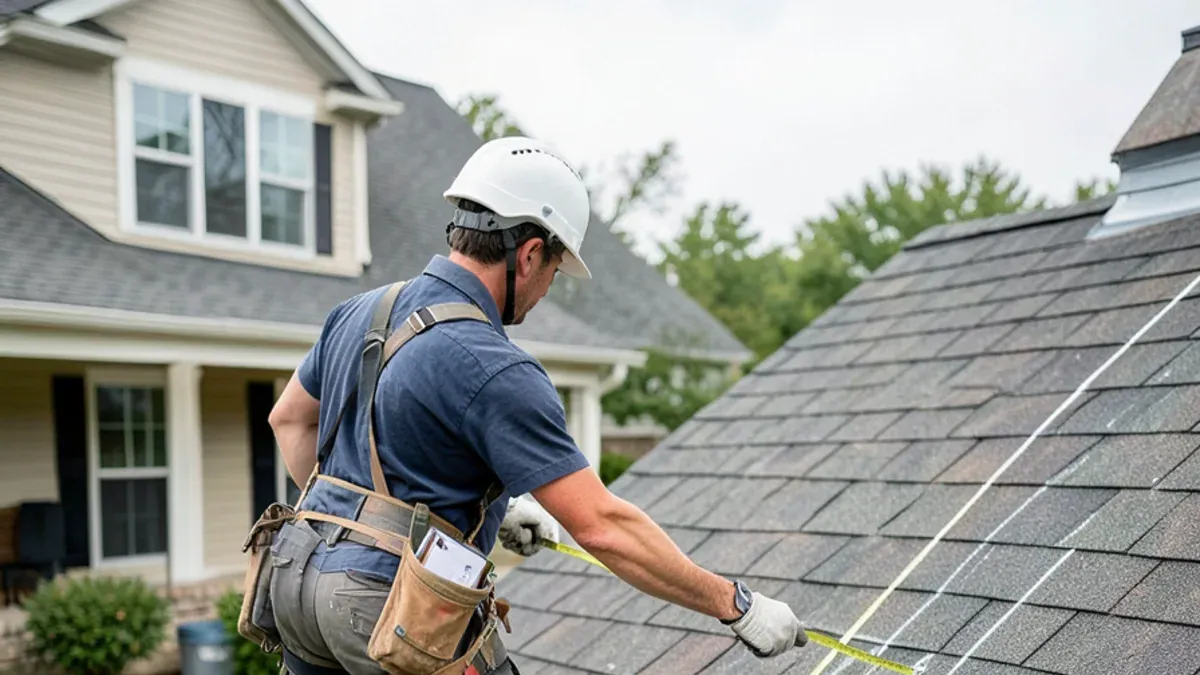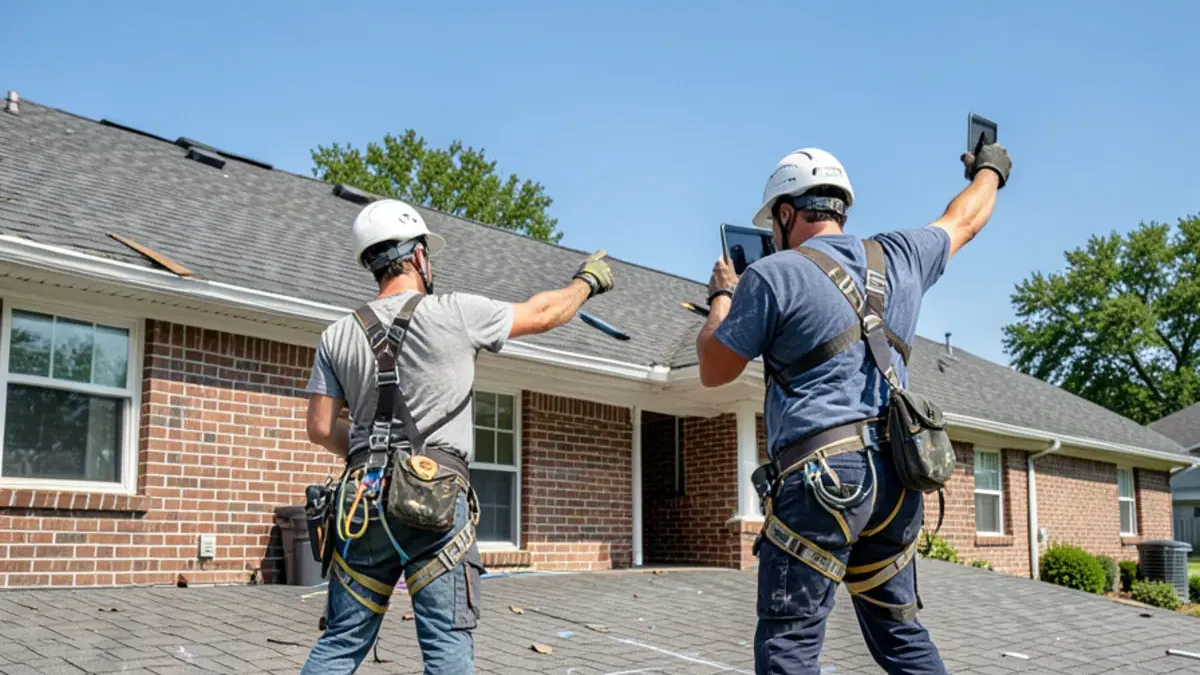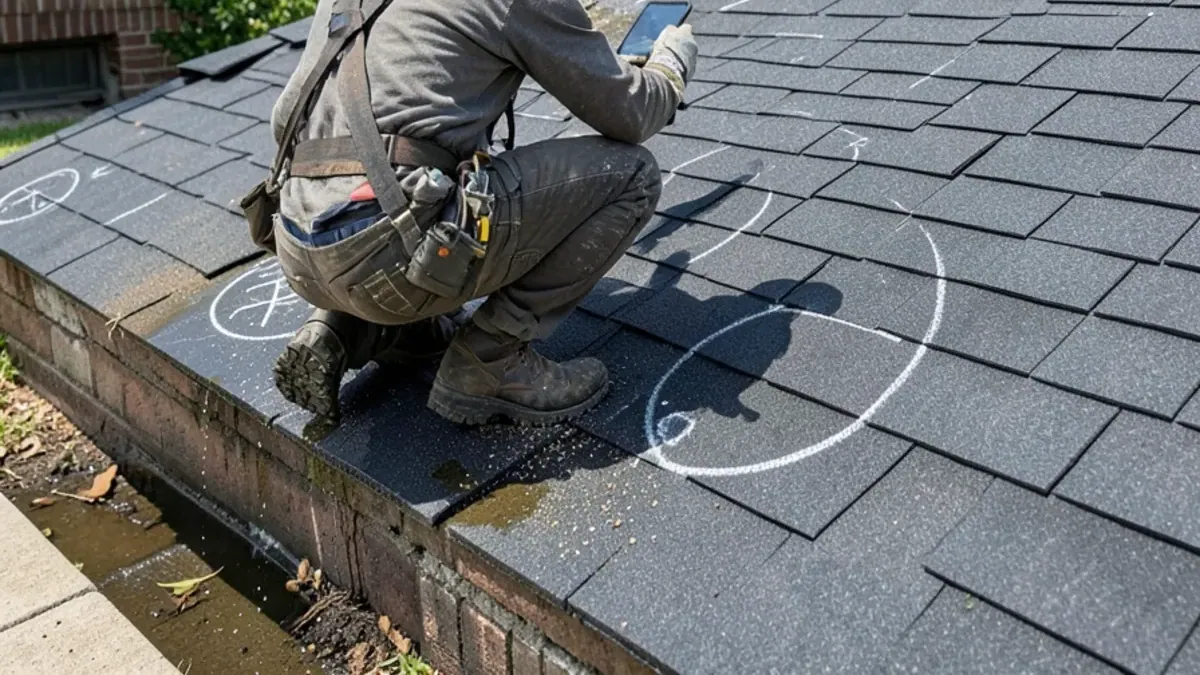
A denial letter is not always the last word on a roof. Sometimes the first inspection was rushed after a big storm, a slope was skipped, or the damage was read as age. Sometimes the denial was right. A re-inspection tells you which, and it builds on the same approach as our Irving roof insurance claim help: careful roof damage documentation and a roofer at the adjuster meeting to point it out.
Roof claim denied? What should you do first?
- Read the letter for the reason. "Wear and tear," "pre-existing," "cosmetic," "below deductible" and "late notice" each need a different response.
- Ask for the adjuster's estimate and photos. You are entitled to understand what the insurer relied on.
- Do not let the roof go. If it leaks, protect the house and keep receipts; your policy expects reasonable steps to prevent more damage.
- Get an independent inspection. Our free roof inspection gives you a second set of eyes before you decide whether to push back.
- Watch the calendar. Your policy and Texas law both have deadlines. Write down every date.
Why do insurers deny or underpay roof claims in Texas?
Most disputes come down to one of three questions. Was there storm damage at all, or is the roof simply worn out? If there was, did it come from the storm on the claimed date? And if both answers are yes, did the estimate include everything the repair actually needs?
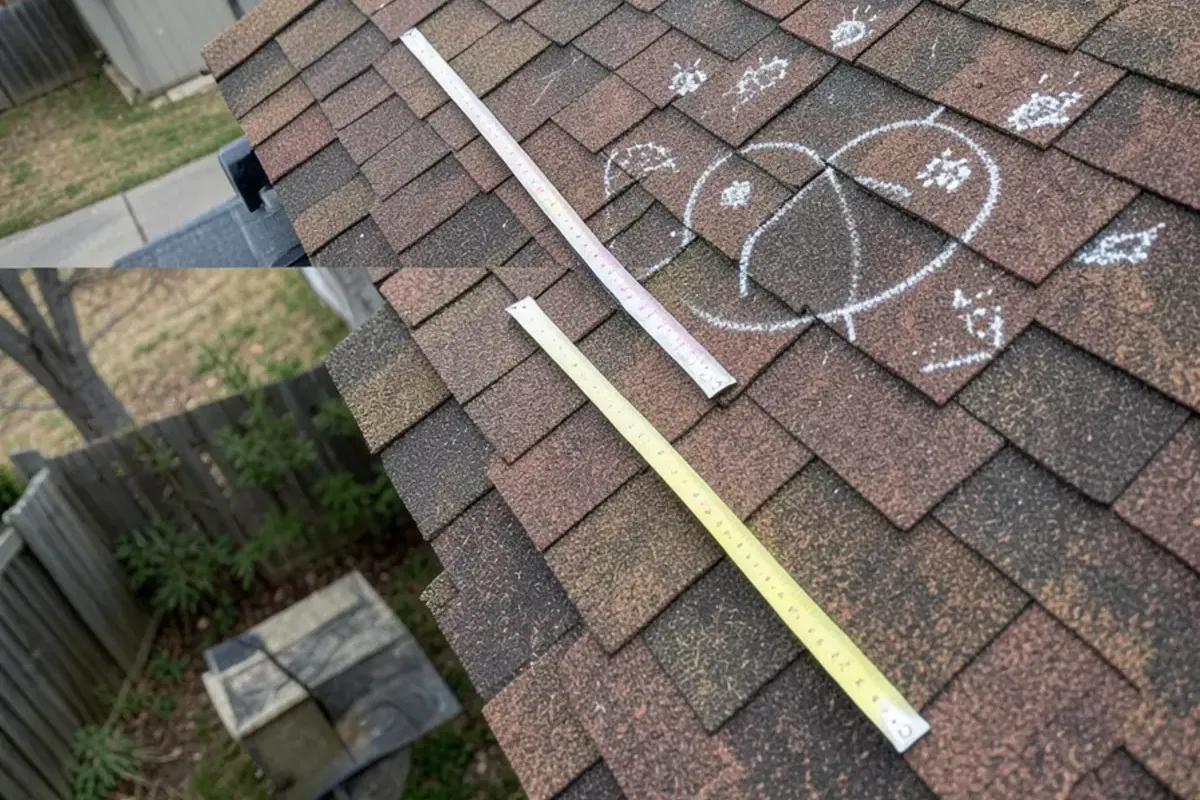
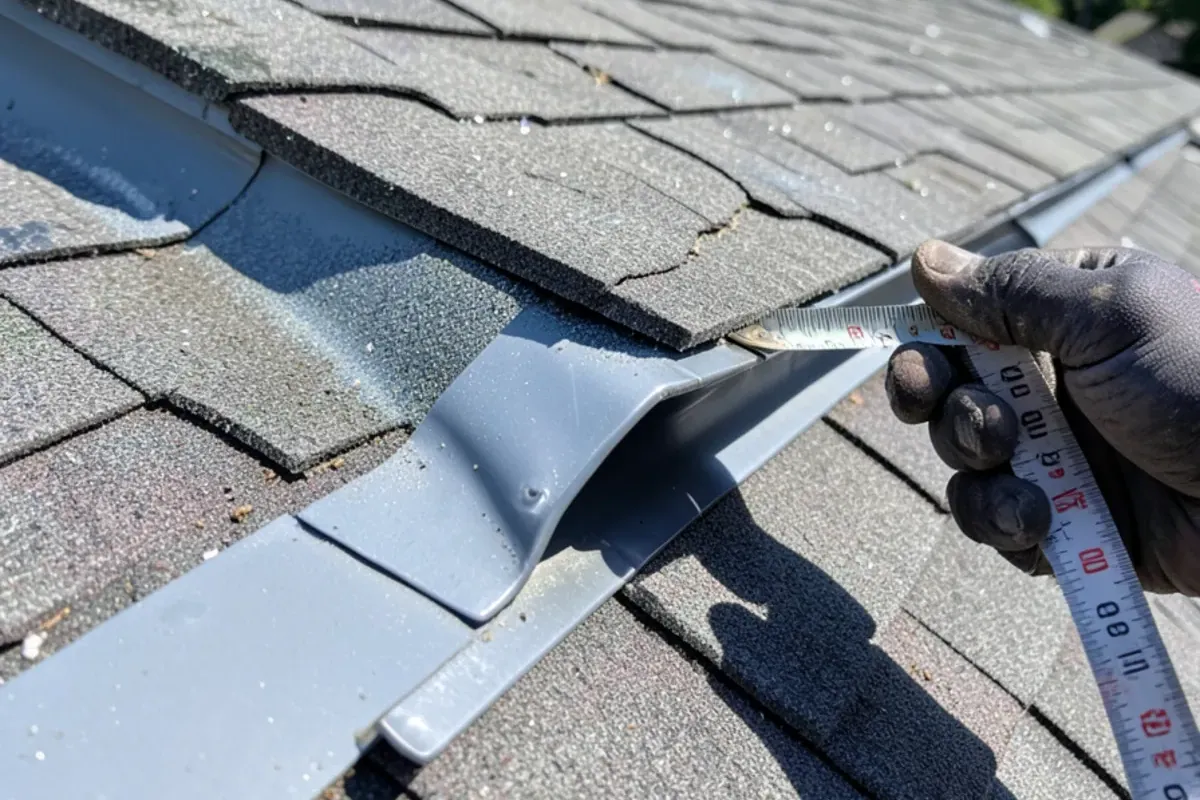
An underpaid roof claim in Texas often fails on the third question: a slope left off, ridge caps or starter rows missing, drip edge or pipe jacks not counted, or code items your city requires on a re-roof. Those gaps are measurable, and measurement is our job.
Local conditions feed both of the first two questions. After a large DFW hailstorm, adjusters can be booked back to back for weeks, and a rushed visit is when slopes get skipped. Irving's housing is old, with a median build year of 1986, so many roofs show sun-worn granule loss next to fresh hail bruises; our report separates the two, impact by impact, so "wear and tear" is either confirmed or answered.
How we help you request a re-inspection of a roof claim
A re-inspection starts from the reason printed in your denial letter, not from a blank page. If the insurer called the damage wear and tear, we look for the marks wear does not leave, such as dented vent caps and fresh fractures on the slopes that faced the storm. If the letter said the loss fell below your deductible, we measure every slope again so the gap is counted rather than guessed.
What you get from us:
- A full re-inspection of every slope, including the ones a first visit often misses.
- New photos and a written report that answer the specific reason in your letter.
- A line-by-line comparison of the insurer's roof estimate with what we measured.
- An explanation, in English or Spanish, of what we found and whether we think the denial holds up.
- A list of documents to request from your insurer, such as the itemized estimate and field photos, if you do not have them yet.
How it runs:
- You share the denial letter and estimate.
- We inspect the roof and document what we find against the stated reason.
- We go over the results with you, including any honest bad news.
- If you choose to push back, you send the request and our report to your insurer.
- If a second adjuster comes out, we can meet them on the roof and show the marked damage.
Questions about denied roof claim re-inspection? Talk to us.
Call for a free inspection and a written estimate. Hablamos español.
- 5.0 on Google (33 reviews)
- Free inspections & estimates
- Se habla español
- Workmanship guaranteed in writing with every contract
Appeal a hail claim denial: who handles each step
Our role ends at the evidence. Texas Insurance Code Chapter 4102 lets only a licensed public adjuster represent you in negotiating with the insurer, and Section 4102.163 bars a contractor that may do your roofing from that role. Beyond a re-inspection, these are the routes Texas homeowners use:
- Appraisal. If you agree damage is covered but not on the amount, most policies let either side invoke appraisal, with an umpire breaking ties.
- Licensed public adjuster. Worth considering for larger or more tangled claims; verify the license with TDI.
- Attorney. For bad-faith concerns or a lawsuit. Chapter 542A of the Insurance Code adds notice steps before suing over a hail or wind claim, which is lawyer territory.
- TDI complaint. The Texas Department of Insurance takes complaints about how a claim was handled and runs a consumer help line at 1-800-252-3439.
Two practical rules also apply once the dispute is settled. No Texas agency licenses roofing contractors, so check a roofer's current City of Irving registration before any work. And a re-roof in Irving needs a city permit, while the city waives it for repairs no larger than 100 square feet.
Reclamo de techo negado: le explicamos en español
Muchas familias reciben la carta de rechazo en inglés y no saben qué significa. We read it with you in Spanish, explain the stated reason, and show you what the roof does or does not support. The decision about what to send your insurer, and who represents you, stays with you.
Cost, workmanship and where we re-inspect
The re-inspection and report are free, and so is an estimate if repairs or a replacement follow. If the claim is approved after all, you still owe your deductible. Under Chapter 707 of the Insurance Code no Texas contractor may cover or rebate it, so treat any such offer as a red flag. Work we perform comes with our workmanship guarantee in writing in the contract; materials fall under the manufacturer's own warranty.
What a disputed roof claim can cost you
The roof work is only one variable. What you spend depends on which route the dispute takes: a re-inspection request costs nothing but time, appraisal usually means paying your own appraiser and half the umpire, and a public adjuster or attorney works under a fee agreement you should read before signing. On top of that sit your deductible and, on actual-cash-value policies, depreciation for roof age. We help you weigh those against the gap our report finds, so you know whether pushing back is worth it. If that gap is a few hundred dollars after depreciation, an appraisal fee can swallow it; if whole slopes were left off the estimate, the math looks very different.
Why homeowners ask us for a second opinion
Homeowners trust us with second opinions because we are blunt about old roofs, because reviewers credit us with explaining insurance coverage clearly, and because 33 Google reviewers have given us a 5.0 average (November 2026). The same inspector who re-documents your roof can attend the second adjuster visit, and the whole conversation can happen in Spanish. The re-inspection and report cost nothing, our photos are dated so they line up with the storm on your claim, and if repairs follow, the workmanship is guaranteed in writing in your contract. We will also say so when a denial looks right to us, because pushing a weak dispute only costs you time. From Irving we re-inspect roofs across the area, including Dallas, Richardson and Plano. Have your denial letter ready and call (725) 745-8803.