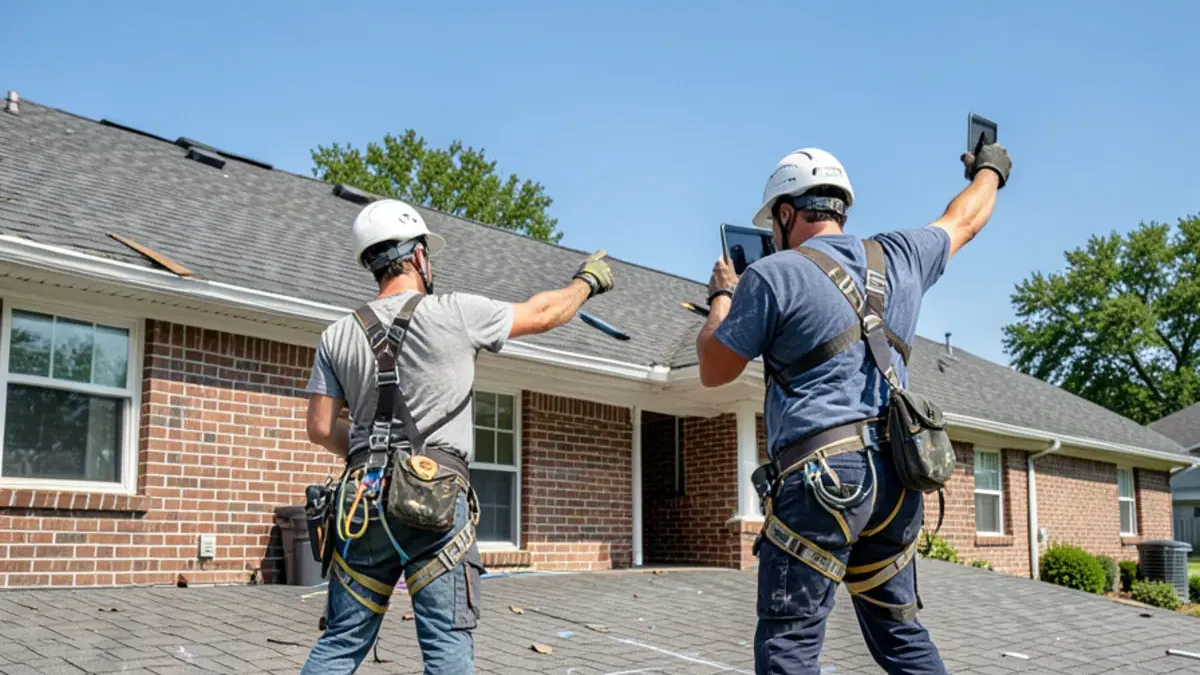
An adjuster's visit decides much of what your claim pays, so we offer to be there. It is one step in our wider roof insurance claim help from Irving, built on the photos and report from our storm damage roof documentation. If the visit goes badly, the next stop is our page on re-inspection when a roof claim is denied.
Should a roofer meet the insurance adjuster on your roof?
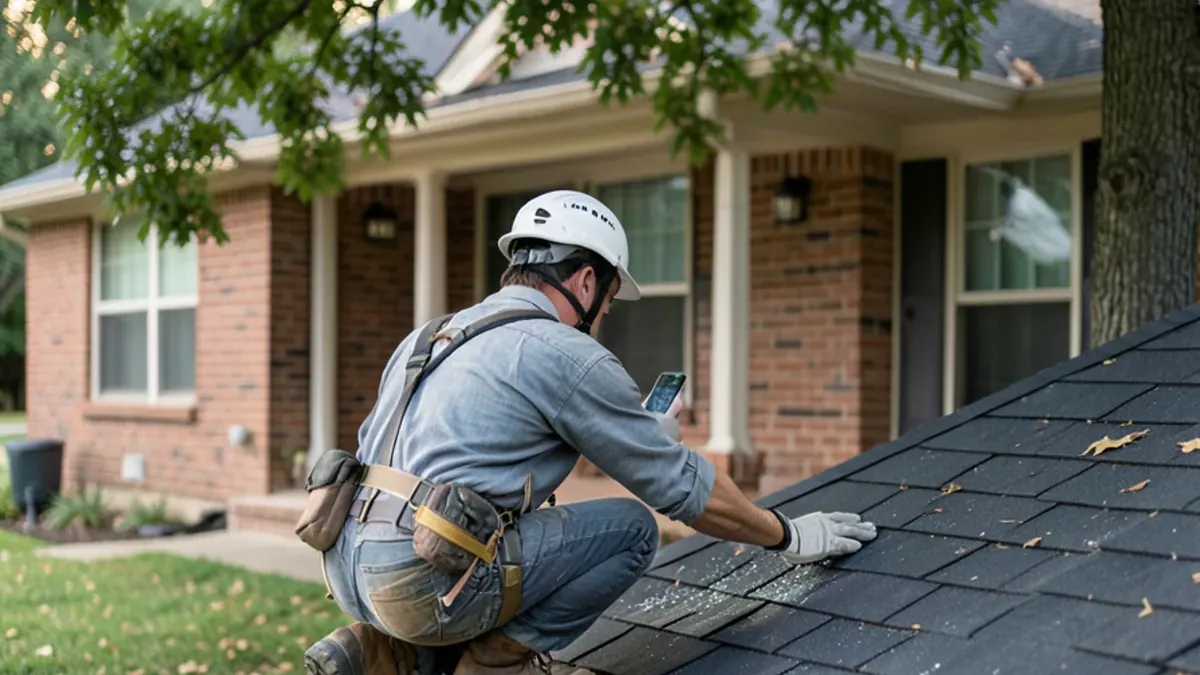
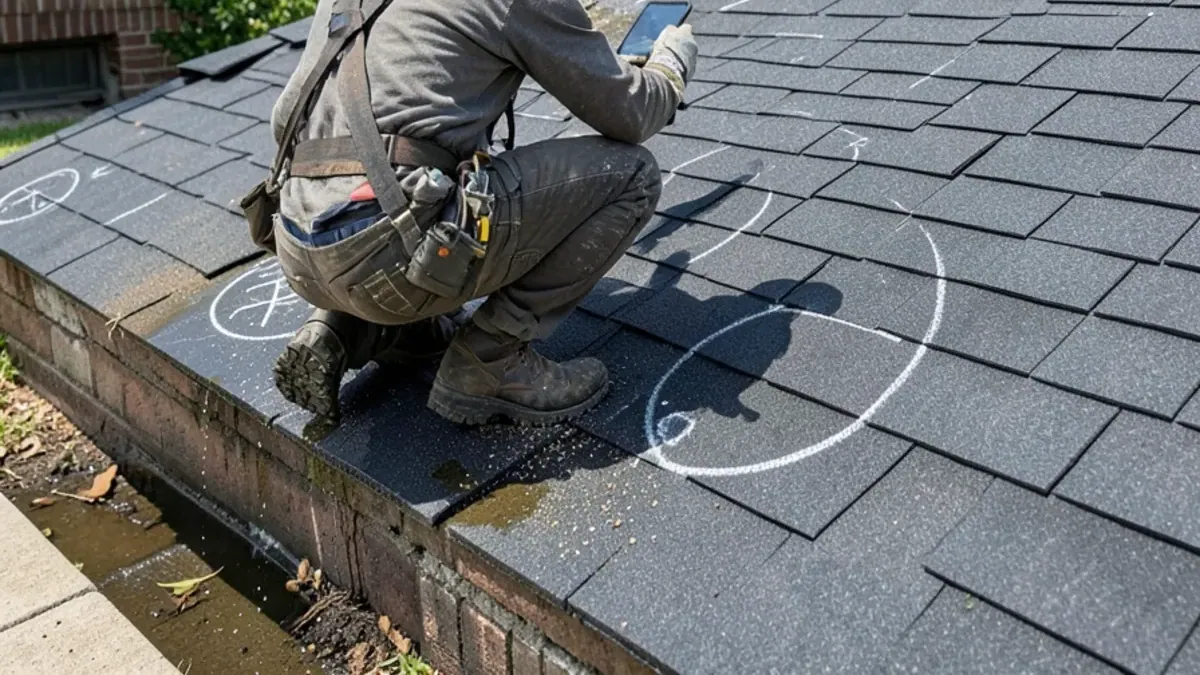
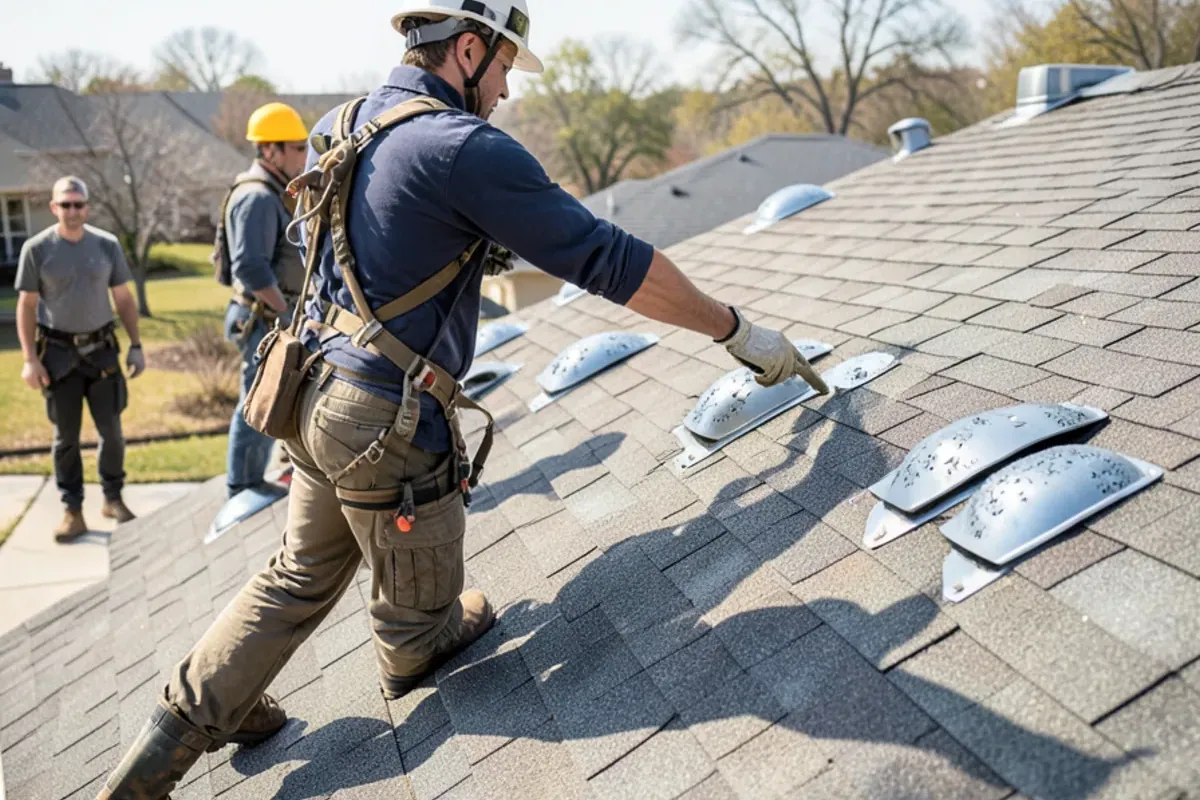
You do not have to have one there, and many claims go fine without. The value of having us attend is simple: the adjuster sees the damage through the eyes of someone who already spent an hour on that roof. Hits are chalked, slopes are labeled, and the soft metals that confirm hail size are easy to point to. In the owner's words, from our replies to Google reviews: "Correctly identifying storm damage to a roof and working with insurance is an essential part of what we do every day."
When having us on the roof helps most
Ask us to attend when hail marks are scattered across several slopes, when an older roof has earlier patches an adjuster could read as wear (Irving's median home dates to 1986), when wind creased tabs without tearing them off, or when the household would rather hear the findings in Spanish. Extension advice from hail states agrees: results improve when an experienced roofer walks with the adjuster.
What does a roof adjuster look for?
Most field adjusters work through a similar list:
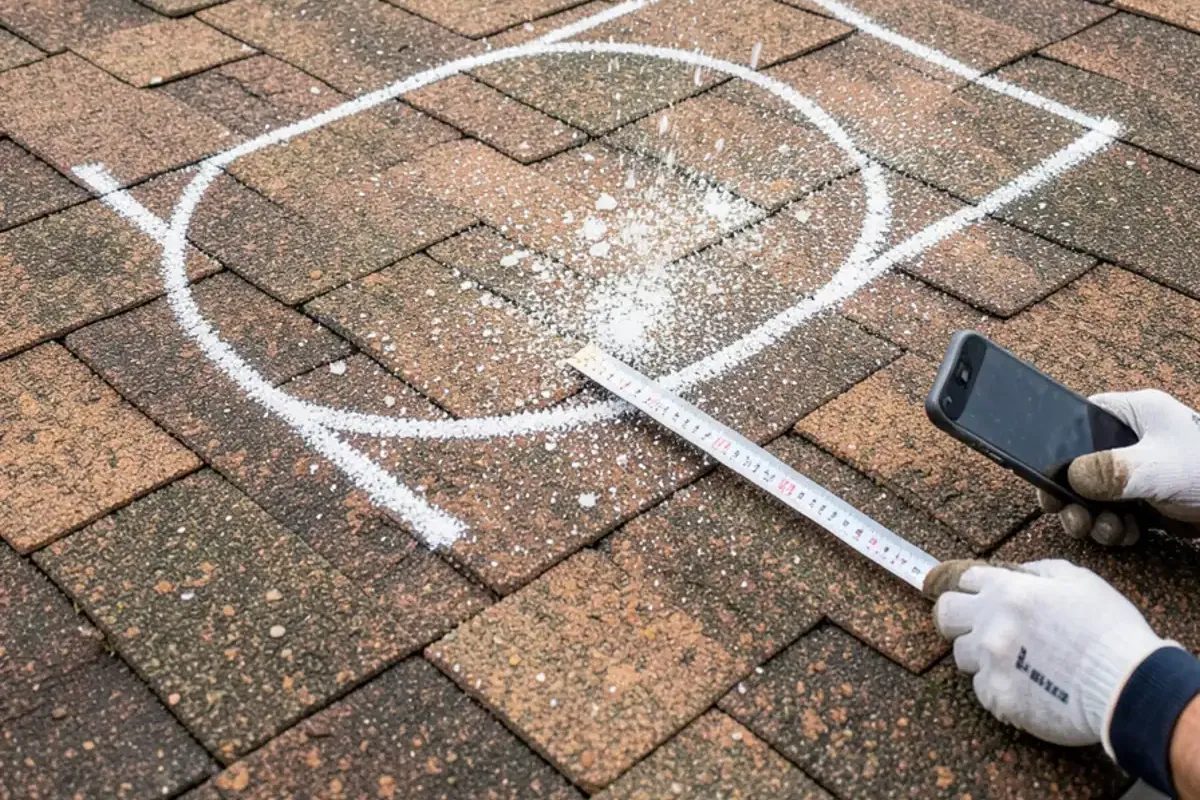
- Hail hits per test square on each slope facing the storm, compared against the insurer's guidelines for that roof type.
- Functional damage, such as fractured mats, exposed fiberglass or punctured metal, as opposed to purely cosmetic marks.
- Wind evidence: creased tabs, broken seal strips, missing shingles and lifted ridge caps.
- Soft metals that confirm hail size and direction.
- Age and condition, including blistering, granule loss from weathering and earlier repairs, which can affect what is covered.
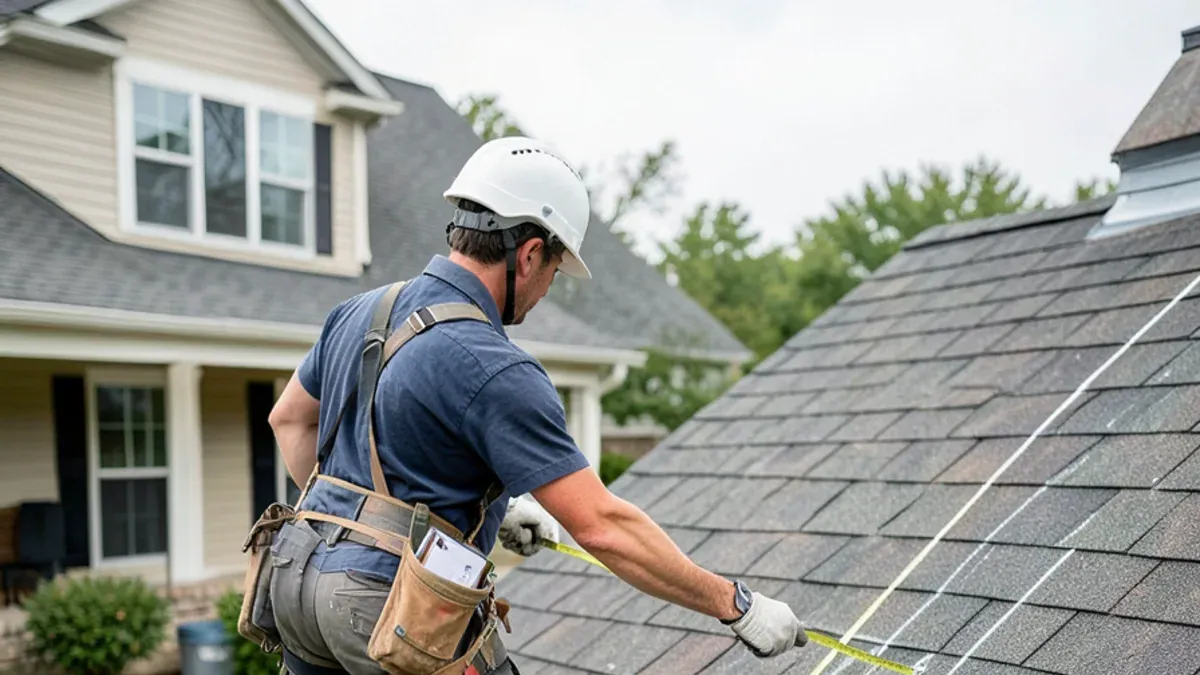
- Roof measurements, pitch and layers, which drive the estimate.
What we bring to the roof adjuster inspection
We arrive with the evidence organized, so the adjuster's roof time goes to looking, not searching. Every attended inspection includes:
- Our printed or digital report with slope diagram and dated photos.
- Chalk marks still visible from our inspection, refreshed if rain washed them out.
- A ladder set and secured so everyone climbs safely.
- Notes on code items in your city that may affect the scope, such as Irving's re-roof permit requirement.
- An inspector who speaks English and Spanish.
- Measurements, pitch and layer count, so the adjuster's figures can be checked against ours later.
While the adjuster works, we photograph any spot they test, mark or lift, so both sets of notes match slope by slope later. We do not bring a contract or an assignment form, and nothing is signed on the roof. If a slope is too steep or wet to walk safely that day, we say so, and the adjuster decides how to inspect it.
How the insurance adjuster hail damage visit usually runs
- Before the visit. You tell us the appointment window and we confirm the documentation is ready.
- Ground walk. The adjuster often starts at ground level, looking at gutters, screens, fences and siding.
- Roof inspection. We climb with the adjuster, take each slope in turn and point to the marked damage.
- Questions. If the adjuster asks about installation details, layers or decking, we answer from what we saw.
- Wrap-up. The adjuster leaves to write the estimate, and we tell you what we observed.
- After the estimate. Show us the scope and we point out any gaps for you to raise with the insurer.
Questions about insurance adjuster meeting? Talk to us.
Call for a free inspection and a written estimate. Hablamos español.
- 5.0 on Google (33 reviews)
- Free inspections & estimates
- Se habla español
- Workmanship guaranteed in writing with every contract
Adjuster meeting tips for homeowners
- Write down the adjuster's name, the claim number and the date of the visit.
- Have your declarations page handy so you know your deductible before anyone mentions it.
- Ask whether the adjuster sees storm damage, and when the written estimate will come.
- Do not sign anything assigning your claim or its proceeds to a contractor; that is not how we work.
Which Texas rules apply when the adjuster visits?
Three rules frame every attended inspection. Texas Insurance Code Chapter 4102 keeps claim negotiation with licensed public adjusters. Chapter 707 bars any contractor from paying, waiving or absorbing your deductible. And Texas has no state roofing license, so check that a roofer holds current City of Irving contractor registration. If the claim leads to a re-roof, Irving requires a permit; its residential roofing handout exempts only repairs up to 100 square feet. In practice, we point out the damage we documented and explain it, but we do not argue the estimate or speak for you on price; that part belongs to you, or to a licensed public adjuster or attorney you hire.
Reunión con el ajustador del seguro, in your language
For Spanish-speaking families, a roof inspection can feel like a conversation happening over your head. Our team can stand with you and explain, in Spanish, what the adjuster is pointing at and why it matters. We translate the roofing part only; questions of coverage or payment are yours to settle with the insurer.
Cost, guarantees and why owners ask us to attend
Your free roof inspection and report come first, and we explain any charges before scheduling anything else. The roof we build carries our workmanship guarantee in writing as part of the contract.
What moves the numbers on the adjuster's estimate
The adjuster's estimate, not our opinion, sets what the claim pays, and a handful of variables drive it: roof area in squares, pitch, number of layers to remove, the shingle or metal type, code items such as drip edge or permit fees, and depreciation for age if the policy settles at actual cash value. A separate wind and hail deductible, common on Texas policies, comes off the top. We compare those lines when you share the estimate.
Less obvious items matter too. Hail hits are usually counted per test square on each slope, so one skipped slope can drop it from the scope entirely. Some policies carry ordinance-or-law coverage that pays for code-required work, others do not; check your declarations page. In Irving, the re-roof permit itself shows up as a line; one third-party schedule lists $125–$325 (Smart Roofing Calculator), and the City sets the actual fee. Many replacement-cost policies hold back part of the payment until the work is invoiced.
Why owners ask us to attend
Owners call us because reviewers say we walked them through every step and made their coverage clearer before they filed, because we hold a 5.0 Google rating from 33 reviews (November 2026), and because the same team can talk to the whole family in Spanish or English. You already hold our dated photos and written damage report before the adjuster arrives, so what we show on the roof matches your copy. We attend inspections in Irving and nearby cities including Euless, Bedford and Hurst. Once you have an inspection date, call (725) 745-8803 and we will plan around it.