Texas law says a roofer cannot waive your deductible. Texas Insurance Code Chapter 707 puts the deductible on the homeowner for any property insurance claim, and a contractor paid from that claim may not pay, waive, absorb, rebate or credit it, or advertise that it will. Any offer to 'take care of' your deductible is a red flag.
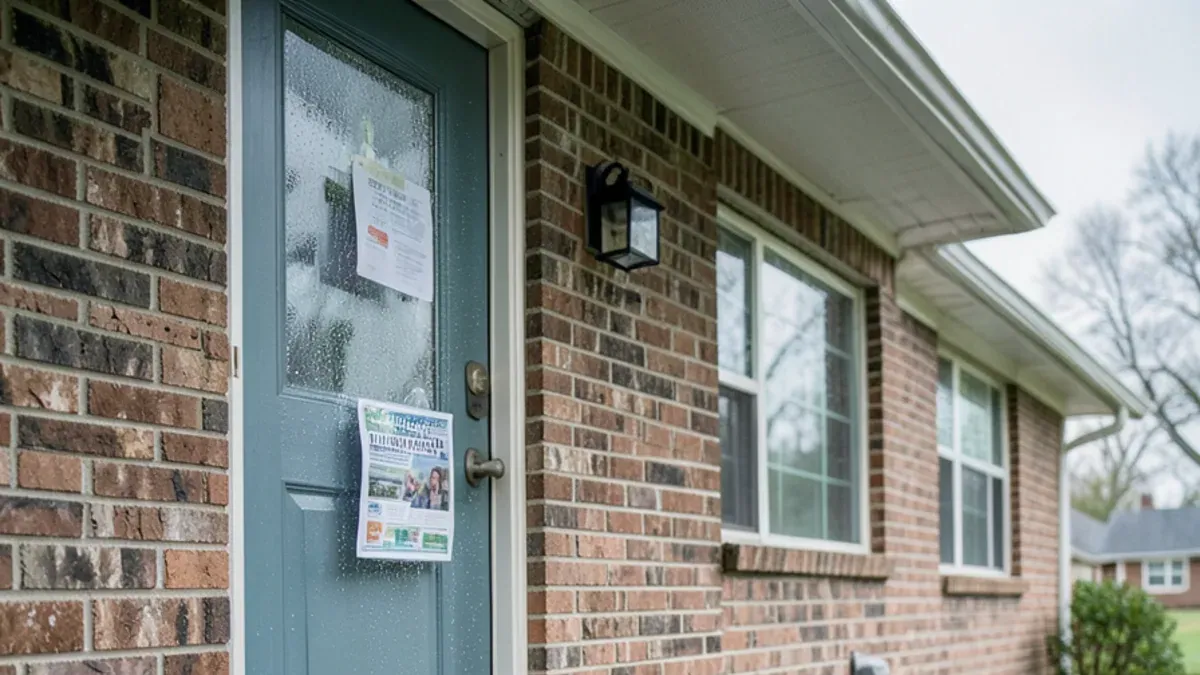
After a hailstorm, the pitch shows up within days: a flyer on the door, a text, or a friendly person on the porch saying, "Don't worry about your deductible, we'll take care of it." In Texas, that promise is not a perk. It is a sign the company is willing to break a state law, and that tells you how it may treat the rest of your claim.
What Texas Insurance Code 707 Says
Texas Insurance Code 707, in effect since September 1, 2019, deals directly with deductibles on property insurance claims. In plain terms:
- The insured pays the deductible. If you file a claim under your property policy, the deductible is yours to pay.
- Contractors cannot help you avoid it. A person or company selling goods or services paid from your claim may not knowingly allow you to skip the deductible or help you do so.
- The ways of avoiding it are spelled out. Paying it, waiving it, absorbing it, rebating it or crediting it back to you are all covered.
- Advertising it is prohibited too. Promising to cover the deductible in an ad, flyer or sales pitch is itself a violation.
- Insurers can check. Your insurer may ask for proof that the deductible was paid.
Violations are a criminal offense under the chapter. The Texas Department of Insurance also notes that Business and Commerce Code section 27.02 requires a notice about deductibles on contracts of $1,000 or more involving an insurance settlement.
Why Texas Made Deductible Waivers Illegal
The reasoning is about who ends up paying. When a contractor "eats" a deductible, the money has to come from somewhere, and the usual source is the claim itself: an inflated estimate, extra line items, or work billed but not done. That raises claim costs, which flow back into premiums for everyone. It also leaves the homeowner exposed, because the claim now rests on numbers that may not hold up if the insurer looks closely.
Want a roofer to look at it?
Free inspection with photos. Se habla español.
- 5.0 on Google (33 reviews)
- Free inspections & estimates
- Se habla español
- Workmanship guaranteed in writing with every contract
How Does the Deductible Come Out of a Roof Claim?
Many homeowners picture writing a check to the insurance company. That is not how it works. The insurer subtracts the deductible from what it pays, and you cover that share of the contractor's price from your own funds. Here is the flow on a replacement-cost policy, using round numbers purely as an illustration:
- The approved scope. Say the insurer approves $15,000 to replace the roof.
- The deductible comes off. With a 1% wind/hail deductible on a home insured for $250,000, the deductible is $2,500. The insurer will pay at most $12,500.
- Depreciation may be held back. If the adjuster depreciates the old roof by $4,000, the first check is $8,500.
- The roof is built. The contractor's price for the approved scope is $15,000.
- The held-back amount is released. After you send the final invoice within the policy's time limit, the insurer pays the remaining $4,000.
- Your share. Insurance has paid $12,500. The other $2,500, your deductible, comes from you.
Your declarations page shows whether the wind/hail deductible is a flat dollar amount or a percentage of dwelling coverage. Percentage deductibles are calculated on the coverage amount, not the claim, so a higher-value home carries a larger deductible even on a small roof claim.
How the "We'll Cover It" Pitch Sounds
A pay-my-deductible offer from a roofer rarely uses those words. These are the versions we hear about most, and what is really behind them:
| What you hear | What it usually means | Allowed under ch. 707? |
|---|---|---|
| "We'll handle your deductible." | The contractor plans to absorb it | No |
| "We'll pay you to put our sign in the yard." | An advertising fee sized to match the deductible | No, if it offsets the deductible |
| "Your deductible comes back as a rebate after the job." | A roofing deductible rebate | No |
| "We'll give you a discount equal to your deductible." | A credit disguised as a price cut | No |
| "Refer two neighbors and your deductible is gone." | A referral credit used to cover it | No, if it offsets the deductible |
| "We'll write the estimate so you won't pay anything." | Inflating the claim | No, and it can be insurance fraud |
The "No-Cost Roof" Scam Behind the Pitch
The bigger offer is the "you won't pay a dime" roof, sometimes advertised with a word we will not repeat here. Under Texas law, a roof paid by insurance is never free to the owner: the deductible is always yours. Companies that lead with this message after DFW storms are often out-of-area crews who will not be around if the roof leaks next year. Watch for related pressure tactics, such as asking you to sign before the adjuster has inspected, or wanting control over your claim.
How We Handle Your Deductible
Our approach is simple and in writing. Your deductible is your responsibility, and our contract says so in the notice Texas requires. We never offer credits, sign fees, rebates or discounts tied to it. If you choose an upgrade the insurer does not cover, such as impact-resistant shingles, we price it on its own line so the numbers stay clean.
What we do on a claim is document and show. We photograph and report the damage, explain the policy terms you share with us, and attend the insurance adjuster meeting to walk the roof and point to what we found. The insurer sets the approved scope, and we build to it. That keeps the claim honest, which protects you if anyone ever reviews it. Owners in Watauga and across northeast Tarrant County hear the same pitches after every storm, and we answer the deductible question the same way everywhere.
We also have an honest conversation when a deductible is a stretch. The legal options are limited but real: ask your insurer whether the claim is likely to clear the deductible before you file, set the deductible aside as soon as the claim is approved instead of spending the first check, and skip upgrades you were considering so the out-of-pocket total stays at the deductible. What we will not do is shrink the scope on paper or move money around to make the deductible disappear. Se lo explicamos también en español: el deducible del seguro del techo siempre lo paga el dueño.
Pay the Deductible, Keep Your Claim Clean
The law is clear and so is the practical lesson. A contractor who breaks the deductible rule on day one gives you little reason to trust their estimate, their work or their guarantee. Learn more about how we support roof insurance claims the legal way, or talk with a roofing contractor in Irving, TX who puts every number in writing. Reach us at (725) 745-8803 for a free inspection and a plain answer about your deductible.
Questions readers ask
Can a roofer give me a discount equal to my deductible?
Is the homeowner in trouble if a roofer waives the deductible?
Where do I report a contractor who offers to pay my deductible?
Do I pay the roof deductible to the insurance company or to the roofer?
Sources
Written by the RJ Premium Roofing team, a bilingual roofing contractor based in Irving, TX. We inspect, repair and replace roofs across Dallas–Fort Worth and document storm damage for homeowners’ insurance claims.